Sid Salter
- For Mississippi, columnist Sid Salter says Proposition 40 is less a model than a case study. “Our state’s economy depends heavily on homegrown entrepreneurs who build family businesses over generations. Whether you agree or disagree with California’s approach, Mississippians should watch closely.”
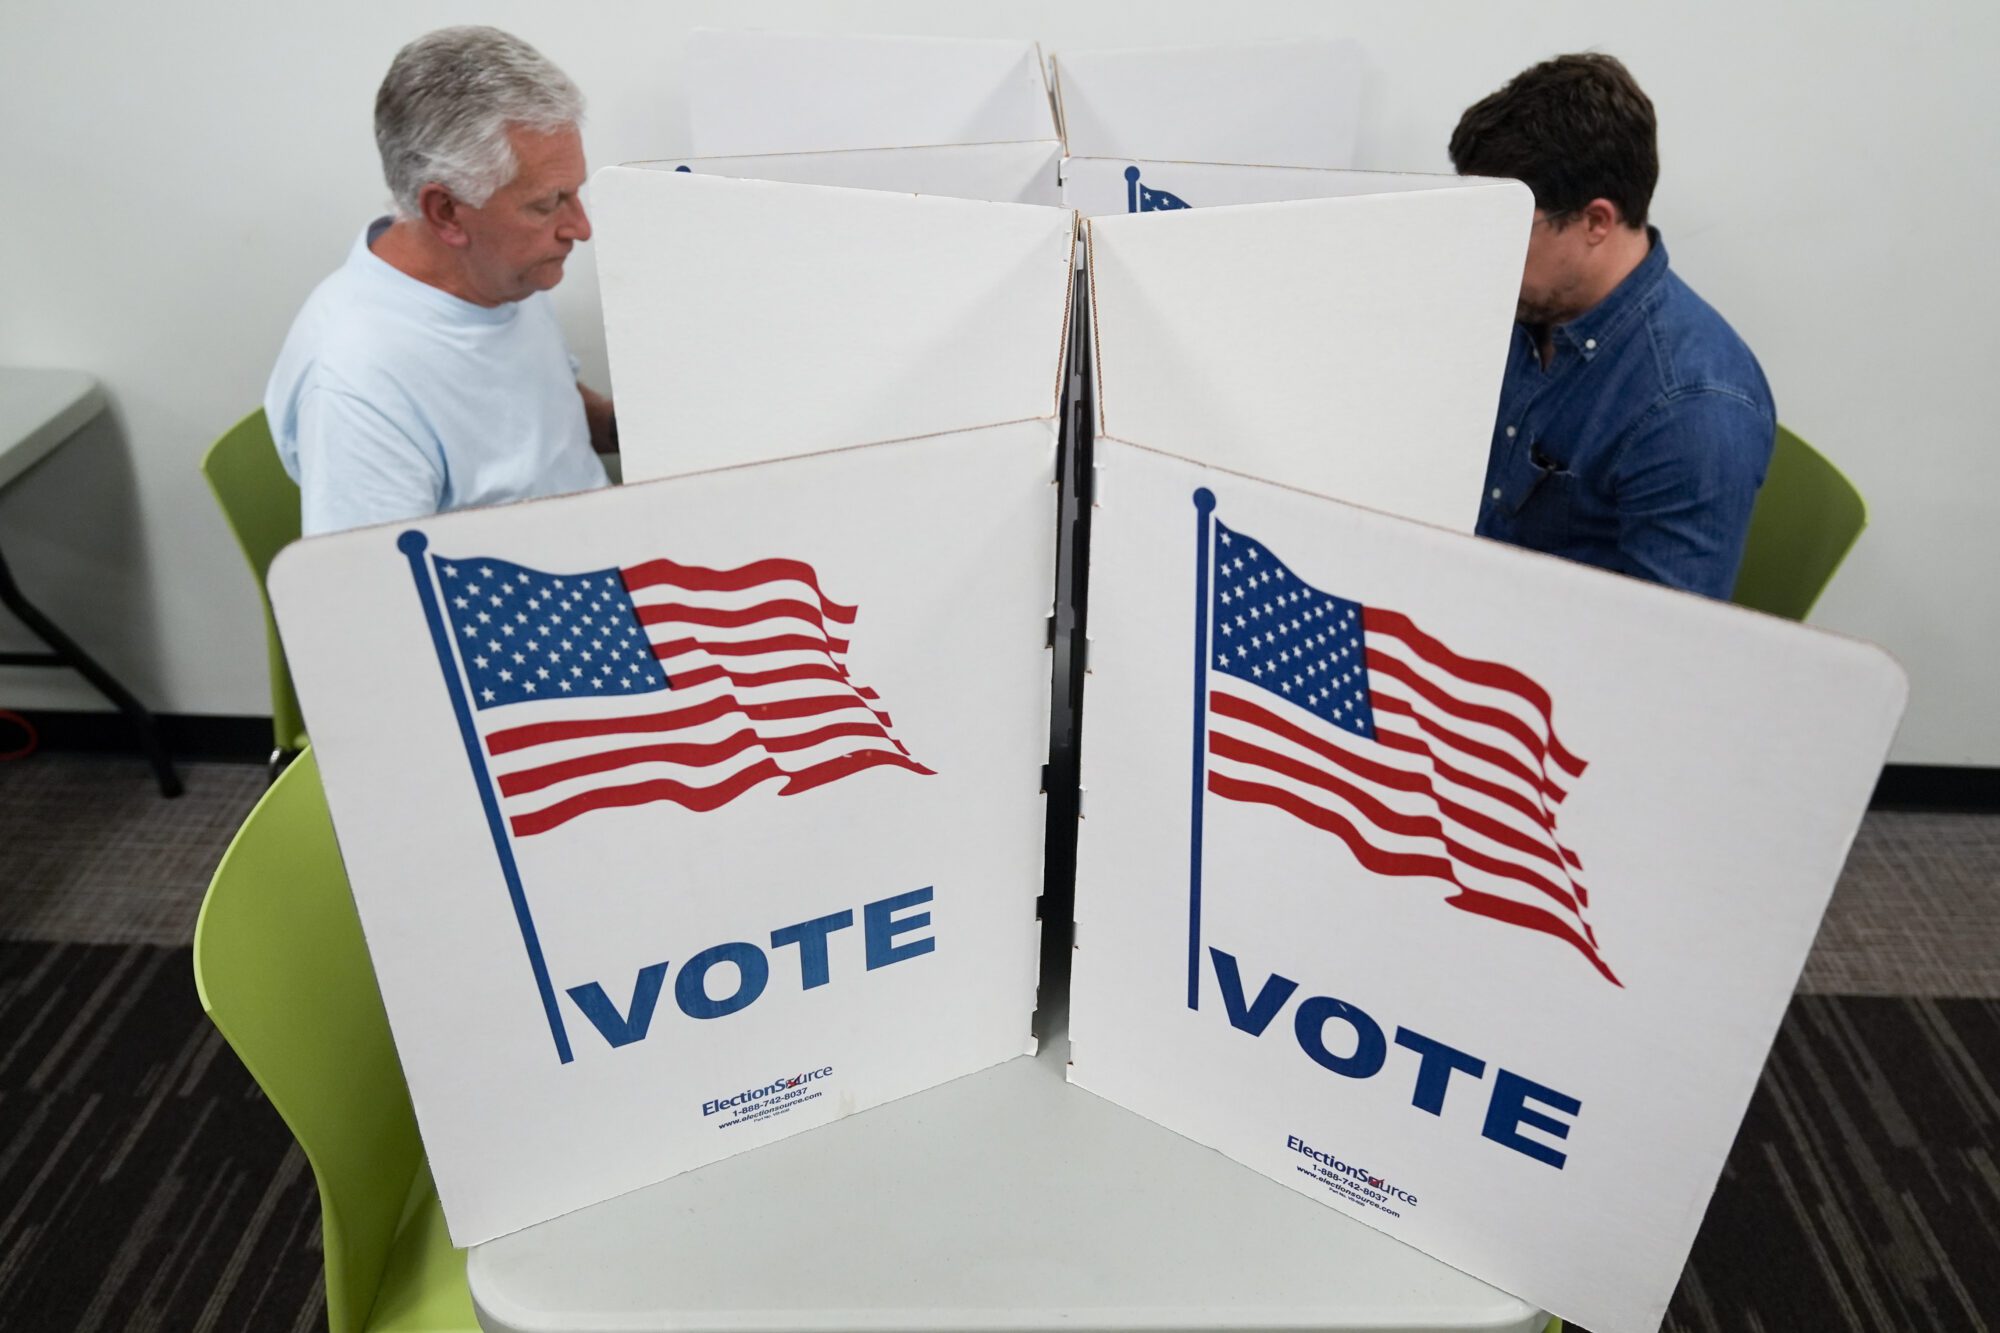
California voters on Nov. 3 decided whether or not to approve Proposition 40, a ballot measure that would impose a one-time 5% tax on the net worth of Californians with more than $1 billion in net worth and use the proceeds largely to fund health care programs.
At this writing, the results were unknown. On the eve of the election, the prediction markets and independent polling suggested the measure would narrowly fail. Let’s hope so. The election’s outcome will be a real test of the relatively new prediction markets.
But supporters claimed the measure could generate roughly $100 billion over five years. Opponents called it a dangerous precedent that taxes wealth rather than income and could drive investment and taxpayers out of the state.
Whatever the outcome, Proposition 40 deserves scrutiny beyond California because it raises a question with national implications: Can a state tax accumulated wealth rather than annual income? Whatever the outcome, other states are likely to take their own crack at wealth taxes.
For generations, American tax policy has operated on familiar ground. Governments tax what we earn, what we buy or use, what we inherit, and the property we own. Proposition 40 ventures into largely uncharted territory by taxing net worth itself.
The proposal is carefully targeted. According to California officials, it would apply only to residents who were billionaires as of Jan. 1, 2026. The state’s legislative analysts estimate that only a few hundred people would be affected.
If Mississippi adopted a California-style wealth tax tomorrow, the affected taxpayers would fit in a phone booth. That fact highlights a central challenge of wealth taxes. The tax base is extraordinarily narrow. When a state relies on a small number of ultra-wealthy taxpayers for considerable revenue, even minor changes in residency, investment strategy, or asset valuation can have significant fiscal consequences.
Supporters view concentration as a virtue. They argue that billionaires have accumulated immense wealth in a system that disproportionately benefited them and that asking them to contribute more during a fiscal crisis is both reasonable and fair. Proposition 40’s backers contended that the revenues would help offset looming health care funding gaps and sustain critical services.
Critics see another danger. They argue that wealth taxes differ fundamentally from income taxes because they require the government to value privately held businesses, startup shares, intellectual property, partnerships, and other hard-to-value assets. Opponents also warn that taxpayers may relocate or restructure their holdings, reducing future revenue.
Then there is the legal question. If Proposition 40 passes, court challenges are virtually guaranteed. Lawyers will test whether California can constitutionally tax net worth in this way, particularly when wealth is tied to businesses and investments spanning multiple states and countries. The measure is likely to face challenges on due process, interstate commerce, residency, and asset valuation.
Yet those predicting an easy judicial defeat may be overstating their case. States have long enjoyed broad authority to tax their residents. Courts generally defer to legislatures on tax policy unless a clear constitutional violation is present. The stronger judicial challenges are likely to focus not on the concept of wealth taxation itself, but on how the tax is applied and administered.
That distinction matters. The greatest threat to Proposition 40 may not be a judge with a gavel. It may be economics. Several European countries experimented with wealth taxes over the years, only to modify or repeal them amid concerns over complexity, capital flight, and competitiveness. Even a constitutionally valid wealth tax can fail as public policy if it yields less revenue than projected or produces unintended economic consequences.
For Mississippi, Proposition 40 is less a model than a case study. Our state’s economy depends heavily on homegrown entrepreneurs who build family businesses over generations. Whether you agree or disagree with California’s approach, Mississippians should watch closely.
If California succeeds in collecting tens of billions while withstanding judicial scrutiny plus avoiding a significant exodus of taxpayers, wealth taxes will gain credibility nationwide. If the measure collapses amid litigation, valuation disputes, or economic backlash, it may become a cautionary tale.
Either way, Californians weren’t merely voting on a tax measure. They conducted a national experiment, and the rest of America, including Mississippi’s two billionaires, are watching.